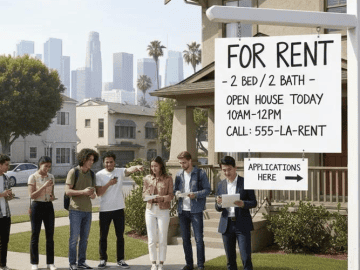

California rents could take nearly two decades to reach today’s estimated monthly cost of buying a home. For Latino families hoping to become homeowners, the affordability gap raises a difficult question: How do you save for a down payment when housing already consumes so much of your income?
For many Latino families in California, renting is supposed to be a step toward owning a home. But when rent takes up a large share of a paycheck and home prices remain high, saving enough to buy can feel like a goal that keeps moving further away.
The numbers help explain the pressure. In September 2026, typical rent in the Los Angeles metropolitan area was $2,929 a month, according to Zillow’s housing market report. The typical home value in the same market was $952,830. Across California, the typical home value was $761,538.
These figures are not a direct comparison of rent with a mortgage payment. They do, however, show the scale of the housing costs facing people who want to move from renting to owning.
For families trying to make that move, the challenge is not just finding a home they like. It is saving for a down payment, qualifying for a mortgage and figuring out whether they can manage the bills that come with owning a home.
Buying a home can offer long-term stability and a chance to build wealth. As owners pay down their mortgages, they build equity in a property. They may also benefit if its value rises over time.
But getting to that point takes money upfront. Buyers generally need a down payment and closing costs. After the purchase, they must budget for mortgage payments, property taxes, homeowners insurance, maintenance and unexpected repairs.
Renters face a different set of pressures. Monthly rent does not build ownership in the property, and housing costs can leave little money to save. But renting is not automatically the worse financial choice: taking on a mortgage that a household cannot comfortably afford can create its own risks.
That is the bind for some aspiring buyers. They need savings to purchase a home, but they must keep paying rent and covering everyday expenses while trying to build those savings.
Childcare, transportation, groceries and other bills can make that process even harder. A family may be able to cover its monthly expenses and still struggle to set aside enough cash to buy a home.
The homeownership gap has a longer history
California’s homeownership gap offers another part of the picture.
A 2024 report from the California Assembly’s Latino and African American Legislative Caucuses reported that, in 2022, the homeownership rate in California was 48.6% for Hispanic households and 64.5% for non-Hispanic white households.
Those figures describe conditions in 2022, not the current homeownership rate in 2026. They also compare broad household groups; they do not tell us why any individual family rents rather than owns.
Still, the gap shows that homeownership has not been equally accessible across these groups. The reasons can differ from one household to another, including income, savings, credit history, job stability, family support and the availability of homes within reach.
On another article we touched on why homeownership is becoming harder for young Latinos in California. The larger question is not whether every renter should buy. It is whether people who want to buy have a realistic opportunity to do so.
Home prices also vary by location. Zillow’s September 2026 data put the typical home value in Los Angeles County at $871,674, compared with $761,538 statewide.
Those are market estimates, not a guarantee that a first-time buyer can find a suitable home at that price. Actual prices vary by neighborhood, property type and condition.
Moving farther from an expensive job center may put more homes within reach. But a lower home price does not automatically mean a more affordable life. A longer commute can add fuel, transit or car expenses and take time away from work and family. Childcare and access to jobs matter, too.
The practical question is not just where a home costs less. It is whether the total cost of living there fits the household budget.
Where buyers can look for help
People who want to buy do not have to figure out every step alone. The California Housing Finance Agency, known as CalHFA, offers mortgage programs and down payment assistance for eligible homebuyers.
Its MyHome Assistance Program offers a deferred-payment junior loan that eligible first-time buyers may use toward a down payment or closing costs. The program has eligibility requirements, and assistance is a loan, not automatically a grant, so buyers should review the terms and repayment conditions before proceeding.
Prospective buyers can start with CalHFA’s homebuyer eligibility guidance and speak with an approved loan officer or qualified housing counselor. Comparing the full cost of owning a home with current rent can help a household decide what is realistic before committing to a purchase.
The goal is a home a family can afford to keep
Renting is not a personal failure, and buying is not the right move for every household. Homeownership can build equity, but it also brings long-term costs and responsibilities.
For Latino families hoping to own a home in California, the challenge is finding a path from paying for housing today to affording a home over the long term. High prices are part of that challenge, but so are the savings required upfront, borrowing costs and the cost of living in the place where a family can buy.
Knowing the numbers, understanding the full cost of ownership and checking which assistance programs may be available can help families make informed decisions. The goal is not simply to buy a home. It is to find one a family can afford to keep.