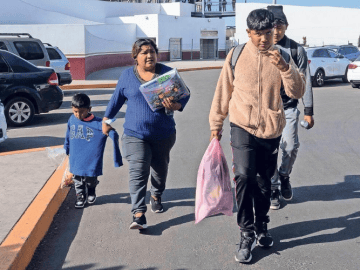

The draft 2026 return asks about citizenship or work authorization. Separate credit restrictions use a different test, while California has its own eligibility rules.
If you file taxes with an Individual Taxpayer Identification Number, the draft federal return for 2026 has a new question to watch: Are you a U.S. citizen, a U.S. national or legally authorized to work?
The question appears on the IRS’s draft 2026 Form 1040, generally used for returns filed in 2027. It doesn’t cancel your ITIN. A separate proposal would limit who can receive money from certain federal tax credits.
For families in Los Angeles and across California, those are separate issues to sort through before filing. There’s also a state benefit worth checking: eligible ITIN filers can claim California credits even when they don’t qualify for the federal Earned Income Tax Credit.
What the new question would ask
The draft gives you one yes-or-no question covering three categories: U.S. citizen, U.S. national or noncitizen lawfully authorized to work. If you file jointly, you and your spouse each have a box to answer.
You wouldn’t be asked to name your specific immigration status. The question would apply beyond ITIN users because it appears on the main tax return.
It also asks about your status when you file. That could differ from your status during the year you’re reporting. For now, the form is still a draft, and the IRS says not to use it to file.
An ITIN is a nine-digit number used for federal tax purposes. The IRS issues it to people who need a taxpayer identification number but aren’t eligible for a Social Security number.
It doesn’t grant immigration status or permission to work. And having one doesn’t mean someone is undocumented.
Why the tax-credit rules need a separate look
The question on Form 1040 and the proposed credit restrictions use different tests. Answering one won’t settle whether you qualify under the other.
Under Treasury and the IRS’s August proposal, the portions of four credits that exceed a taxpayer’s tax liability would count as federal public benefits. The credits cover earned income, children, higher education and adoption.
To receive that money, a filer would need to be a citizen, national or fall within the legal category “qualified alien.” Having permission to work doesn’t automatically meet that test.
The draft Schedule 3-A would calculate the affected amount and ask about that eligibility. For a joint return, one spouse could meet the proposed status requirement, but the couple would still have to meet the credit’s other rules. The restriction wouldn’t cover every kind of refund, including money returned because too much tax was withheld from wages.
Some limits already exist. The federal Earned Income Tax Credit requires qualifying Social Security numbers. An ITIN doesn’t qualify its holder for it.
For the Child Tax Credit, current IRS guidance requires a Social Security number valid for employment for you, or one spouse if filing jointly, and each qualifying child. Having a U.S.-citizen child doesn’t, by itself, make the family eligible.
The proposed credit rule would apply to tax years ending on or after its final publication. When it becomes final would therefore matter for 2026 returns.
Questions about privacy have a longer history. Parriva reported on the IRS–ICE data-sharing agreement in April 2025. Since then, a September 8 appeals court ruling upheld preliminary restrictions on a specific IRS sharing procedure, finding challengers likely to show it violated federal law.
The opinion recounts the Center for Taxpayer Rights’ testimony that data-sharing fears had made immigrant taxpayers less willing to seek its help. That describes concerns about the sharing policy; it doesn’t measure the new question’s effect. The ruling also leaves room for disclosures that federal tax law permits.
Practical guidance: Before you file
Start with the final IRS form and instructions for the year you’re reporting. The draft question doesn’t erase a filing obligation or invalidate an existing ITIN.
Check whether your number needs renewal under existing IRS rules. An ITIN expires after three consecutive tax years without use on a federal return. That rule is separate from the proposed question.
Ask about California credits available to eligible ITIN filers, including CalEITC, the Young Child Tax Credit and Foster Youth Tax Credit. Each has its own requirements.
If you need help preparing a basic return, the IRS’s Volunteer Income Tax Assistance program offers free service to qualifying taxpayers. Use the IRS locator or call 800-906-9887. Before visiting, confirm that the site can handle your return and ask what to bring.
Parriva’s coverage of Direct File’s cancellation and other filing options provides additional background. Check current program terms before choosing a service.
Bring your questions about tax numbers, credits and filing requirements to a qualified preparer. Have them review the federal and California rules separately so your family can meet its obligations and claim the benefits it qualifies for.