
California high schools must begin offering a standalone personal-finance course in 2027-28, with the course becoming a graduation requirement for the class of 2031. LAUSD is already preparing and a new $1.3 million investment will expand financial-education programs for its students.
California is about to make personal finance part of the high-school experience for students across the state.
Beginning in the 2027–28 school year, every California public high school must offer a standalone personal-finance course. Starting with students graduating in 2030–31, completing the course will be required for graduation.
The California Department of Education’s Personal Finance curriculum guidance says the course is intended to give students practical knowledge about managing money, credit, debt, taxes, insurance, investing and other financial decisions they will face as adults.
For families in Los Angeles, the change is arriving as LAUSD expands financial-literacy education.
City National Bank announced Sept. 24 that it will invest more than $1.3 million over three years to expand its Dollars + Sense financial-education program for LAUSD high school students. The program uses curriculum and training from EverFi and will include financial-education resources, educator training, workforce-readiness experiences and scholarships.
But the bigger story for parents and students is not the donation.
It is this:
What will students actually learn?
California’s new personal-finance curriculum is built around 13 required subject areas.
Students will learn the basics of banking, including checking and savings accounts and how to minimize fees.
They will learn how to create and manage a budget and understand the relationship between employment, income and take-home pay.
The curriculum also covers:
- Credit and credit scores
- Debt and interest
- Loans, including student loans
- Insurance
- Taxes and tax forms
- Investing and building wealth
- Consumer protection, scams and fraud
- College and career financing
- Charitable giving
- Financial decision-making and behavior
The state curriculum also allows schools to address practical issues such as buying versus leasing a vehicle, renting an apartment, buying a home, digital banking, digital wallets, cryptocurrency and predatory lending.
California-specific programs and resources, including Cal Grant and CalKIDS, can also be incorporated into the course.
For families trying to understand how education costs connect to these financial decisions, Parriva’s explainer on California college options for immigrant and undocumented students provides additional context.
There are two dates families should remember.
2027–28: California public high schools must offer the standalone personal-finance course.
2030–31: Students must complete the course to graduate.
The requirement comes from Assembly Bill 2927, which was enacted in 2024. The State Board of Education adopted California’s Personal Finance Curriculum Guide in March 2026.
The California Department of Education’s implementation information provides the curriculum guide and resources for schools and educators preparing for the requirement.
California has therefore moved beyond simply encouraging schools to teach financial literacy.
It has created a statewide course requirement.
What about LAUSD?
Los Angeles Unified was already moving toward expanded financial education before the statewide requirement takes effect.
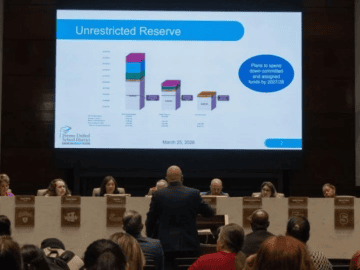
In September 2025, the LAUSD Board of Education approved a resolution calling for a new personal-finance class for high school students and broader financial-literacy instruction across the district’s curriculum. The district identified subjects including budgeting, saving, banking, credit and investing.
The district’s financial-literacy and economic-justice announcement provides additional details about LAUSD’s plans.
LAUSD schools have also been offering financial-literacy programs before the statewide requirement. Now the district is getting additional support.
City National said its Dollars + Sense program was active at 137 LAUSD schools during the 2025–26 school year, reaching 17,212 students and involving more than 800 educators in financial-literacy training. Those figures are reported by City National and describe its own program.
The new three-year investment is intended to expand those efforts as LAUSD prepares for the statewide requirement.
For broader context on the district and the challenges facing Los Angeles schools, Parriva’s coverage of LAUSD and California education provides additional background.
The state has established the required subject matter, but California’s curriculum guide is designed to support districts and educators in developing courses.
That means the statewide requirement does not necessarily mean every student will sit through an identical class using the same lessons or materials.
Schools and districts still have decisions to make about course design, scheduling, instructional materials and teacher preparation.
The California Department of Education is providing resources and professional-learning opportunities to help districts prepare. The department says educators are already participating in training and that California schools have begun offering standalone courses ahead of the statewide deadline.
For parents, that makes a practical question worth asking their school or district:
When will my student’s school offer the course, and what will it look like?
Why the LAUSD investment matters, but isn’t the whole story
The $1.3 million investment gives LAUSD additional resources at an important moment.
City National says the expanded program will provide digital and classroom resources aligned with California’s 13 required topics, along with teacher professional learning. It will also expand workforce-readiness experiences and scholarships.
The bank also reports that students participating in its program during the 2025–26 school year showed increases in self-reported confidence in areas such as budgeting, evaluating purchases and maintaining good credit.
Those results come from City National’s program reporting; they are not an independent evaluation of California’s statewide requirement.
California’s new requirement is much broader than any single private program.
The state has established the framework. Districts and schools now have to turn that framework into classroom instruction.
What parents should watch for
Families do not need to wait until 2030 to start paying attention.
The important period is beginning now.
Over the next several school years, parents can watch for:
Course availability: When will their high school begin offering the standalone class?
Course placement: Which students will take it and when?
Curriculum: What textbooks, digital resources or other materials will the school use?
Teacher preparation: What professional development will teachers receive?
College and career connections: How will the course address financial aid, student loans, apprenticeships and career decisions?
Real-world skills: Will students actually practice budgeting, reading pay stubs, comparing credit options and understanding taxes or primarily learn the concepts through lectures?
Those details will determine what the statewide requirement looks like in an individual student’s classroom.
California is turning personal finance from an optional subject into part of the public-school graduation pathway.
Students will be expected to learn about money well beyond basic budgeting—from credit and taxes to insurance, loans, investing, consumer protection and paying for education and career training.
For LAUSD students, that transition is already underway.
The new $1.3 million investment can help expand the district’s existing financial-literacy work, but the larger change is coming from the state: California public high schools must offer the standalone course beginning in 2027–28, and students graduating in 2030–31 and later will have to complete it.
For families, the next question is no longer whether financial literacy belongs in high school.
It is how well their school will teach it—and whether students leave the classroom ready to use it in real life.
For readers interested in the financial issues facing California families and entrepreneurs beyond the classroom, Parriva’s coverage of California small-business financing and access to capital provides related information.